


Arcadia eFuels’ own 2023 roadmap projected its first Danish plant would begin producing eSAF this year. The offtake agreement Uniper signed this week instead expects first deliveries only “from the early 2030s,” a slip of at least four years from the project’s original target, for a facility that had completed front-end engineering design but had not yet reached a final investment decision as of the most recent independent tracking.
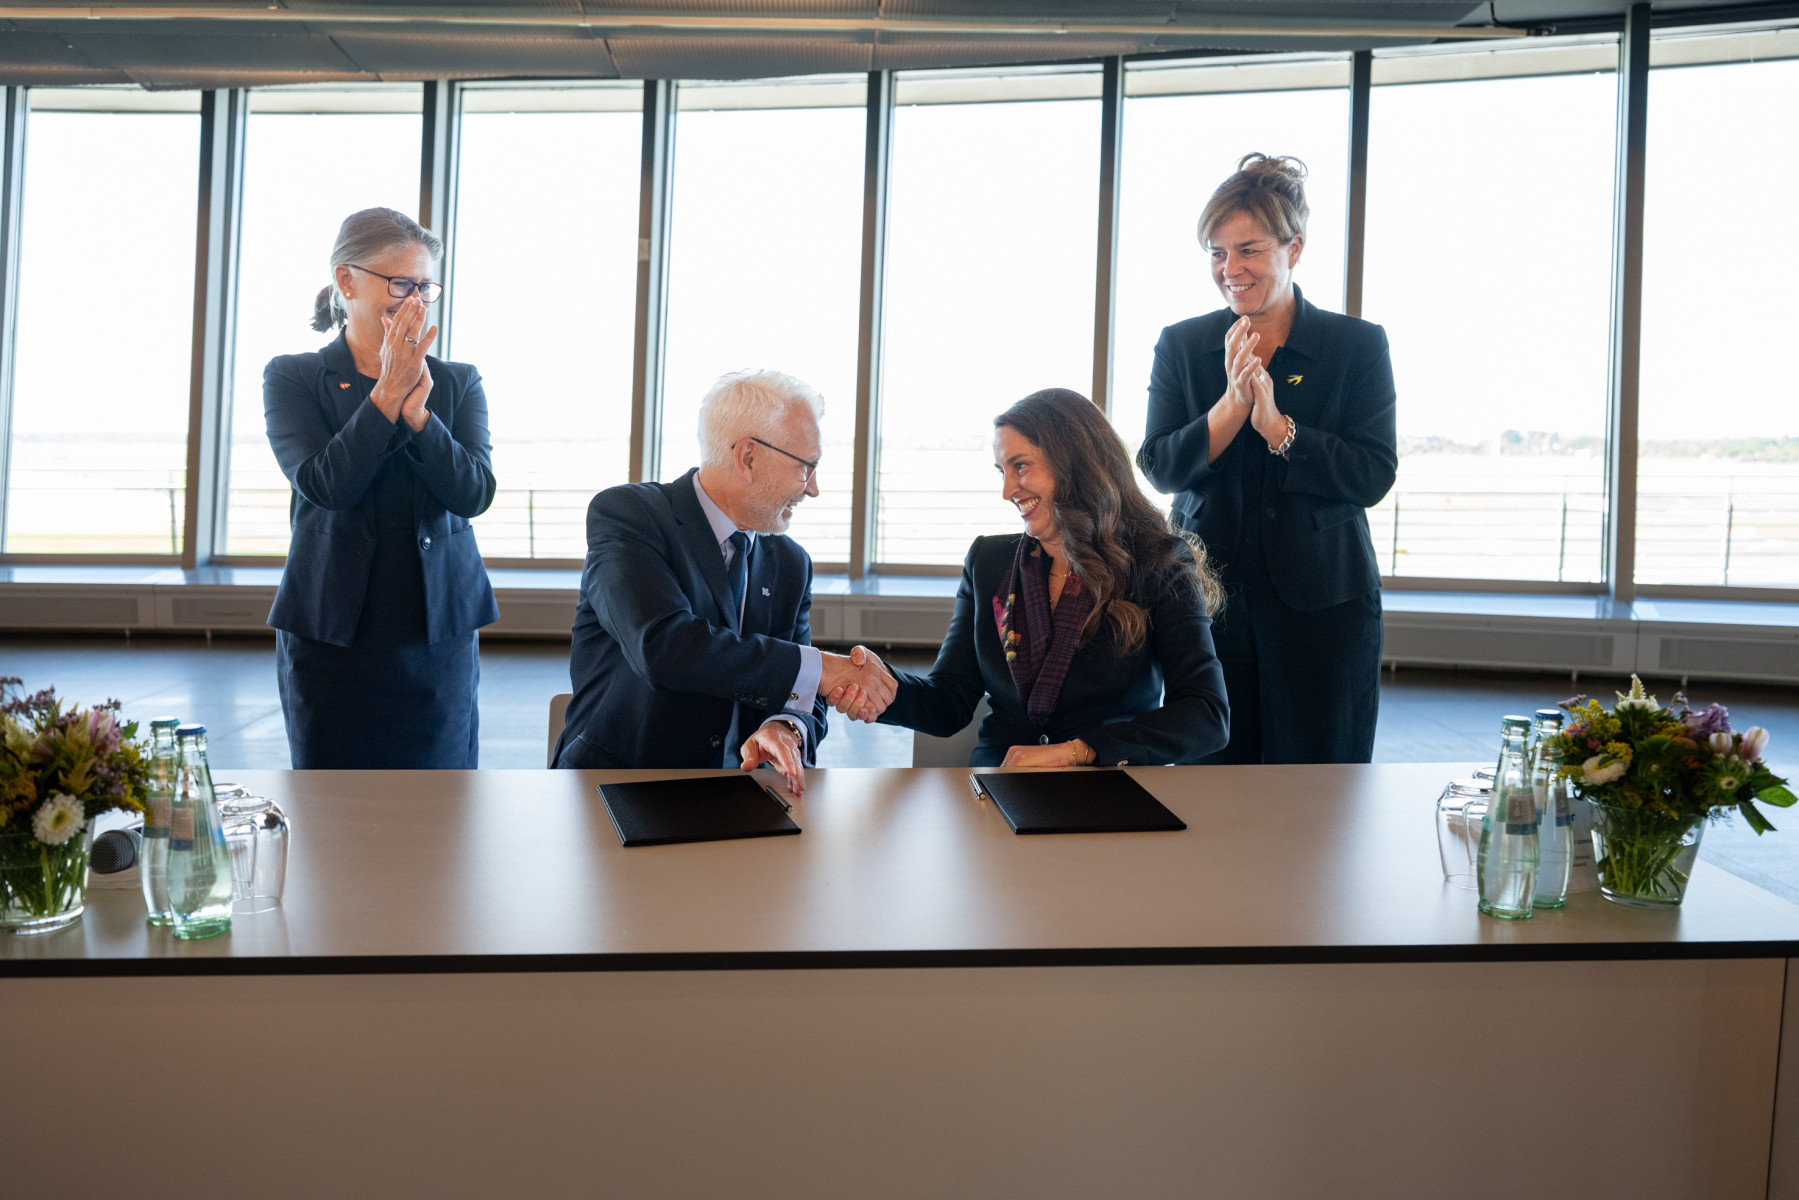
Uniper’s commitment to buy 40,000 metric tons of eSAF annually for more than a decade from Arcadia eFuels’ Project Endor in Vordingborg, Denmark, is not a modest slice of that facility’s output. Endor’s total planned capacity sits at roughly 80,000 tonnes of eSAF annually, meaning this single agreement, described by both companies as one of the largest eSAF offtake deals to date, accounts for close to half of everything the plant is designed to produce. That concentration means Endor’s remaining commercial viability still depends on Arcadia securing comparable offtake commitments for the other half of its planned capacity, a gap this week’s announcement does not address.
The timeline gap matters because of how eSAF, or synthetic sustainable aviation fuel produced through power-to-liquid conversion of green hydrogen and captured CO2, actually gets built. Arcadia completed front-end engineering design for Endor in May 2024, working with Technip Energies on the process design and Hitachi Energy on electrical infrastructure, but independent tracking of the project as recently as this year described it as still awaiting a final investment decision. Commercial-scale e-fuel plants of this type typically require three to four years to build and commission after FID is reached, meaning even a final investment decision taken this year would put commissioning toward the very end of the decade at the earliest, a timeline that leaves little margin within the “early 2030s” supply date now attached to the Uniper agreement, and none at all if FID slips further.
That slippage sits against a European Union mandate structure with specific, binding numbers attached. The bloc required 2% of fuel available at regional airports to be SAF in 2025, rising to 6% by 2030, with eSAF specifically required to reach 1.2% of the total from 2030, rising to 5% by 2035. Meeting that 2030 eSAF requirement across the EU and EEA will require approximately 552,000 tonnes of eSAF, according to industry analysis, implying that roughly eight facilities the size of Endor would need to be operational by that date to avoid a supply shortfall. Endor’s own now-disclosed early-2030s supply timeline suggests it may not be running by the 2030 deadline itself, let alone the seven additional comparable projects the same analysis found still need to reach operation elsewhere in Europe within the same window.
The broader competitive picture adds a further complication to the framing of this deal as evidence of European eSAF momentum. Despite Europe holding roughly half of the world’s announced eSAF production capacity on paper, the first final investment decision for a large-scale e-SAF plant, and the largest eSAF offtake agreement prior to this one, were both secured by US-based developers rather than European projects, a pattern analysts at Transport & Environment have cited in warning that Europe risks losing the first-mover advantage its early project pipeline appeared to establish. Arcadia eFuels itself is a US-headquartered company pursuing its flagship project in Denmark specifically to serve EU mandate compliance, an arrangement that illustrates how the commercial pull of ReFuelEU’s binding targets is shaping where American developers choose to build, even as the underlying project timelines continue slipping against the mandate’s own compliance dates.
Uniper CEO Michael Lewis’s framing, that the challenge now is moving SAF “from promising projects to industrial scale,” is an accurate description of exactly where Endor sits: a project with completed engineering design, a large anchor customer, and EU Innovation Fund backing, but without the final investment decision that would convert those commitments into construction. A long-term offtake agreement of this size is typically what allows a project at this stage to reach financial close, which is the specific and real contribution this deal makes. It does not, on its own, resolve the two harder constraints still standing between Endor and the fuel Uniper has agreed to buy: a construction decision that has not yet been made, and a delivery date that has already moved several years past the project’s own original target before a single ton of eSAF has been produced.