


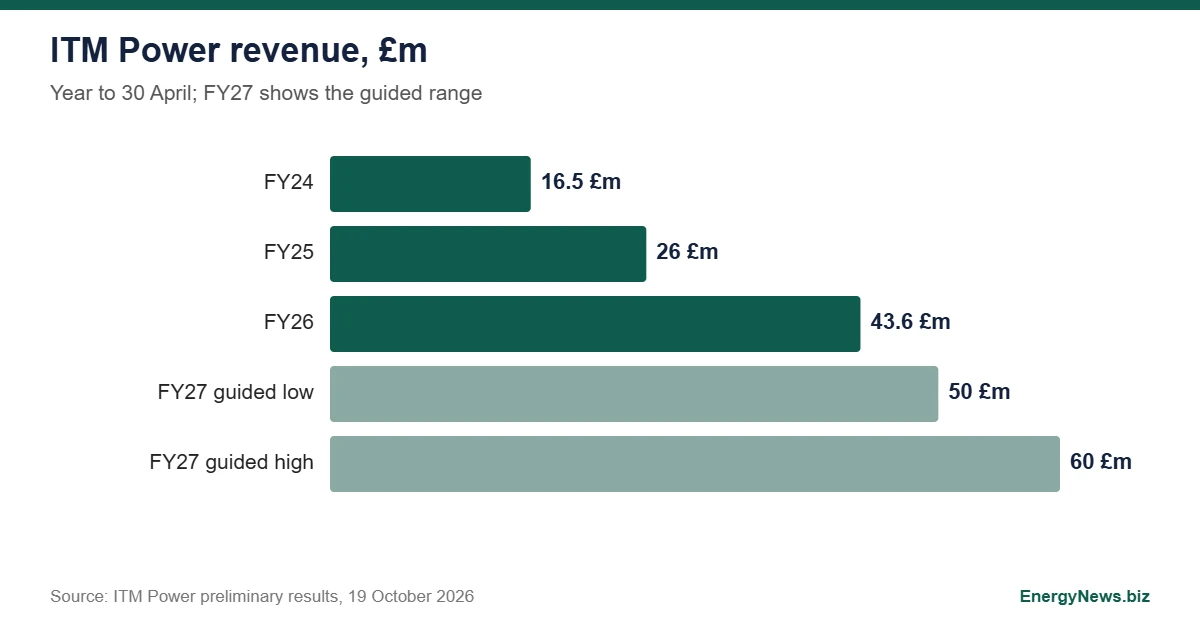
ITM Power reported revenue of £43.6m for the year to 30 April 2026 on 19 October 2026, up 68% from £26.0m, with an adjusted EBITDA loss of £20.2m against £33.0m a year earlier. Cash ended the year at £215.6m.
The growth is real and the loss is narrowing. The cash guidance is the line to read twice: FY27 cash is guided to £170m to £180m, a fall of £35.6m to £45.6m from the year-end balance, in a year that includes the capex for the Chronos manufacturing line.
What the filing shows
Revenue grew 738% over three years, from £16.5m in FY24. Adjusted EBITDA, a non-statutory measure, improved by £12.8m. The gross loss fell from £23.7m to £6.1m, after £7.5m of factory cost under-absorption and £5.0m of manufacturing losses or inventory write-off provisions. Backlog held at £144.0m, and 83% of it is now profitable contracts, up from 60% in April 2025.
Revenue, and who paid it
Product sales were £40.7m of the £43.6m. One unnamed customer accounted for £25.6m, about 59% of revenue, and a second for £8.8m. Europe took £41.0m. By sector, Power reached £24.0m from £1.9m, while Industry fell from £20.4m to £13.7m. Deliveries recognised in revenue were 153 MW, against 40 MW in FY25.
The filing does not name the customers or give prices per megawatt, so the mix cannot be tested further from the document itself.
The cash line
Cash rose £8.6m in FY26, but the cash flow statement shows £40.1m from issuing shares, the Great British Energy investment. Before that issue, cash fell about £31.5m. Net cash used in operating activities was £24.0m, from £20.0m. The FY27 guidance implies a larger fall than that, partly from Chronos spending, and a £46.5m grant from the Department for Energy Security and Net Zero is drawn down as spend is incurred, according to the filing.
The directors’ forecast to 31 October 2027 expects the group to stay cash positive without further fundraising, and a stress case with no customer receipts also stays cash positive for 12 months.
Hydropulse: heads of terms, not an order
The filing describes Heads of Terms for a 150 MW green hydrogen project between Hydropulse, the company’s build, own and operate business, and a European oil refinery, with a planned 10 year contract. A joint FEED study is under way and a final investment decision is targeted in 2027. The company says it would be its largest commercial commitment to date. No contract value is disclosed.
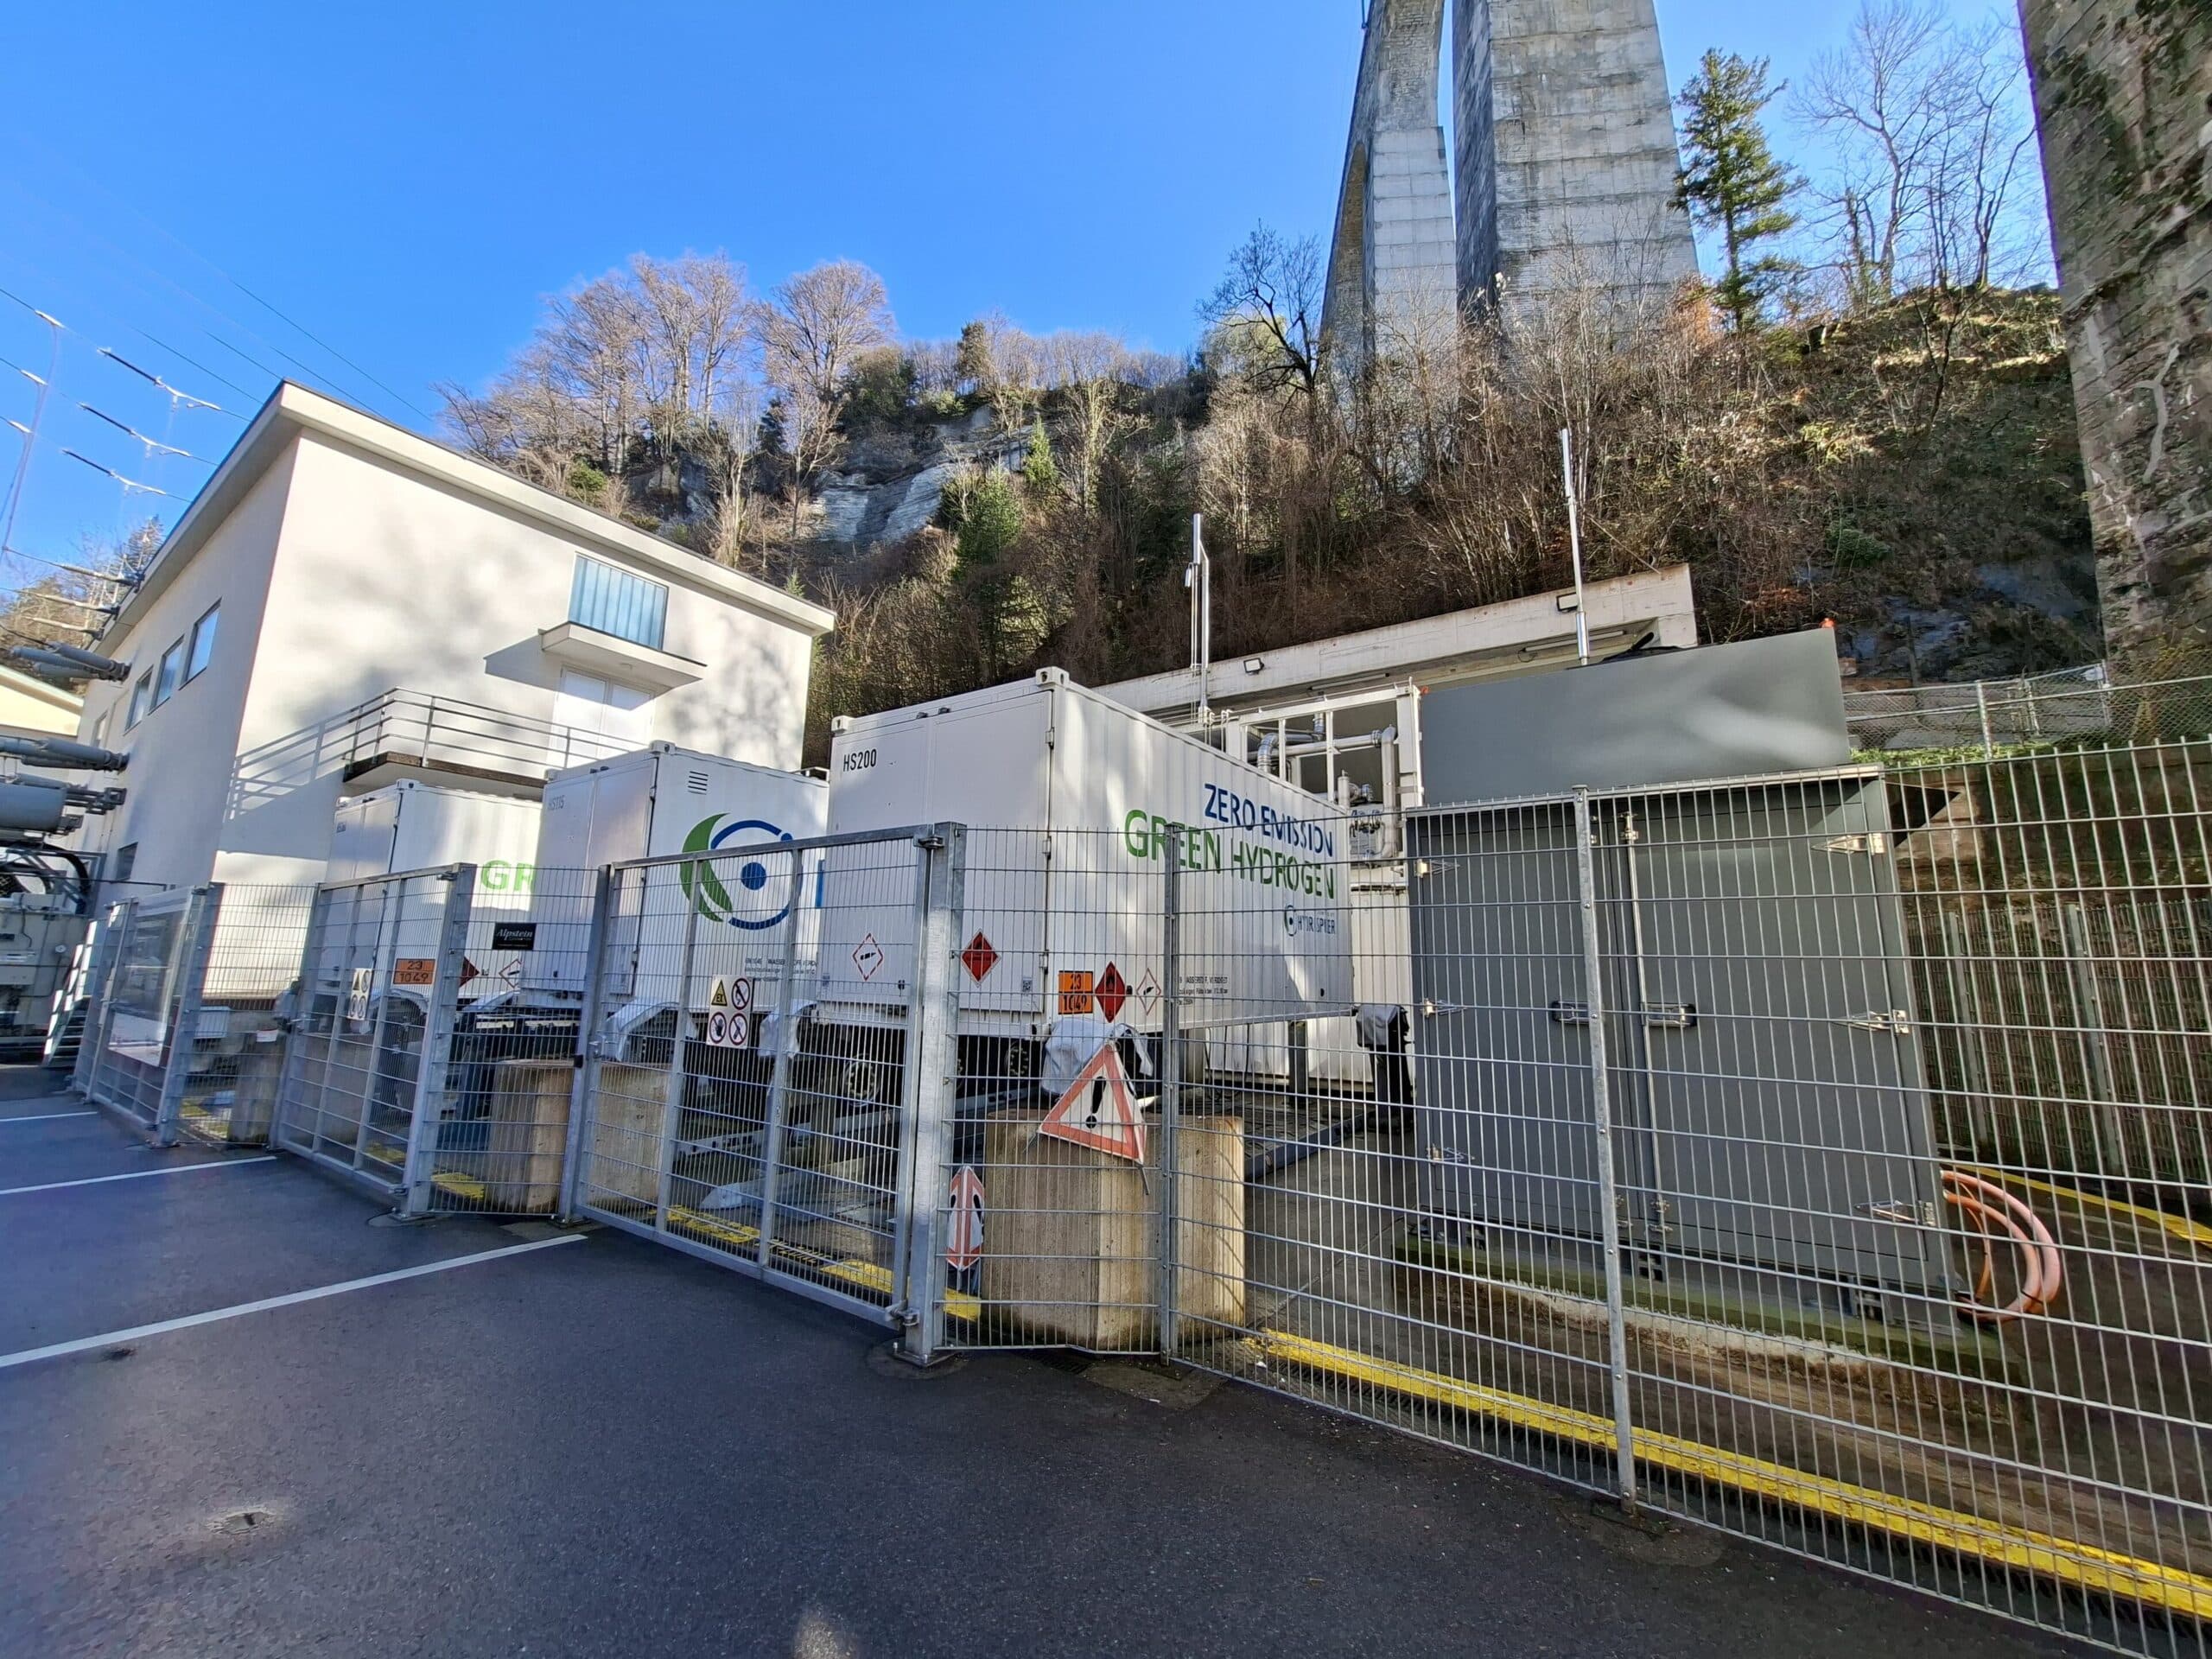
Context for the sector: the first 100 MW plant at RWE’s Lingen site, built with ITM equipment, is operating, and a second 100 MW unit is on track for completion in this financial year. Earlier coverage of European electrolyser orders is here: green hydrogen and wind in Ireland.
The tests ahead
Three dated checks decide whether the guidance holds: Lingen 2 completing by 30 April 2027, the refinery FEED reaching a decision in 2027, and interim results against the £50m to £60m revenue range. Until the refinery project reaches FID, the backlog of £144.0m is the contracted base.
Add EnergyNews.biz as a preferred source on Google